Data current: October 19, 2026 · Florida · 13 min read
Fifty-one Medicare Advantage plans will not exist in Florida next year. If one of them is yours, a letter has already arrived telling you so, and in my experience it gets read once, filed, and treated as bad news.
It is not only bad news. That letter opens a door that stays firmly shut for almost everyone else on Medicare — the right to buy a Medigap policy without answering a single health question. It is the one time the insurance company cannot say no, and it closes 63 days after your coverage ends.
I am Vivian Soto, an independent bilingual insurance agent at VS Healthcare Solutions in Orlando. Here is how to tell whether your letter is the one that opens that door, what the three deadlines actually are, and the single sentence in the federal rules that closes the door for good if you miss it.
First: which letter did you get?
Two letters go out in the autumn and they look almost identical — same envelope, same plan logo, same dense type. They mean completely different things, and only one of them is worth money.
The Annual Notice of Change is the routine one. Every plan has to get it to you by September 30, and it says: your plan continues next year, and here is what is changing about it. Higher copays, a different drug tier, dental trimmed back. Annoying, sometimes expensive, but your plan still exists on January 1.
The non-renewal notice is the other one. It says the plan is leaving Medicare or leaving your area, and that your coverage ends after December 31. Medicare’s own handbook puts it plainly: plans “can decide not to participate in Medicare for the coming year. In these cases, your coverage under the plan will end after December 31. Your plan will send you a letter explaining your options.”
Only the second letter opens the Medigap door. An Annual Notice of Change — even a brutal one that doubles your specialist copay — does not, and no amount of being unhappy with the changes will create the right. This is the single most common misunderstanding I correct in October, and it is an expensive one, because people assume they can leave for a Medigap plan whenever their Advantage plan gets worse. You generally cannot. You can only leave for another Advantage plan, or go back to Original Medicare and face medical underwriting on the Medigap application.
Three windows, and they do not all close on December 7
Nearly everyone treats December 7 as the end of the world. For most people on Medicare it roughly is. If your plan is non-renewing, it is not — you get two extra windows that other people do not, and knowing that is the difference between a rushed decision in November and a considered one.
| Window | When | What it lets you do |
|---|---|---|
| Open Enrollment | Oct 15 – Dec 7, 2026 | Pick any 2027 plan. Coverage starts January 1 — no gap. |
| Special right (non-renewal) | Through the last day of February 2027 | Join another Medicare health plan. Coverage starts the month after you enroll, so January may be uncovered. |
| Medigap guaranteed issue | From 60 days before coverage ends, to no more than 63 days after | Buy certain Medigap policies with no health questions — only if you move to Original Medicare. |
| Medicare Advantage Open Enrollment | Jan 1 – Mar 31, 2027 | If you landed in an Advantage plan and it is wrong, switch once. This does not restore the Medigap right. |
The honest reading of that table: December 7 is still the date you should be working to. The February window exists and it is real, but a plan joined in January starts February 1, which leaves you a month on Original Medicare alone — no drug coverage, no out-of-pocket maximum, and a Part D late-enrollment penalty risk if you drift. Use the extra time as insurance against a mistake, not as permission to wait.
The Medigap door — and the sentence that closes it
Here is the part worth the most money, and the part almost nobody is told.
Normally, once you are past your first six months on Part B, a Medigap insurer in Florida can ask about your health and decline you. Diabetes with complications, a recent cardiac event, COPD — any of them can end the application. That is medical underwriting, and it is why people who went into Medicare Advantage at 65 often find they cannot leave later.
A non-renewal suspends that. Under federal law you get a guaranteed issue right, and CMS states the conditions precisely in Choosing a Medigap Policy: you have the right if your plan “is leaving Medicare,” “stops giving care in your area,” you move out of the service area, or the plan’s network “has a significant change.”
And then, in the same box, the sentence that undoes it for most people:
“You only have this right if you switch to Original Medicare (rather than join another Medicare Advantage Plan).”
Read that twice if you have a letter on the table. The most natural thing to do when your Advantage plan disappears is to pick another Advantage plan — the mailers are already arriving, the premium is often $0, and it feels like replacing like with like. It is also the choice that spends your guaranteed issue right without you ever knowing you held one. Six months later, when the new plan turns out to have the wrong network, the Medigap underwriting questions are back and the answer may be no.
That is not an argument for Medigap. Medigap carries a real monthly premium where an Advantage plan may carry none, and for plenty of households the Advantage plan is genuinely the better buy. It is an argument for making that comparison once, deliberately, while both options are actually open to you. This year, for 51 plans’ worth of Floridians, both are open. They will not both be open in 2028.
Which Medigap policies you can actually buy
The guaranteed issue right is not a right to every Medigap plan on the market. CMS lists it precisely: Medigap Plan A, B, C, D, F, or G sold by an insurance company in your state.
With one important qualifier. Plans C and F are closed to anyone who became eligible for Medicare on or after January 1, 2020. If that is you, your guaranteed issue right is to Plan D or Plan G instead. In practice most people in this situation are comparing Plan G, which is the closest thing to full coverage still sold to new enrollees.
The timing, also from CMS: you can apply as early as 60 days before your Advantage coverage ends, or by the date given in your plan’s termination notice, and no more than 63 days after it ends. One detail that catches people: the Medigap policy cannot begin until your Advantage coverage actually ends. You are lining up January 1, not buying something that starts tomorrow.
You will also need a standalone Part D drug plan. Original Medicare and Medigap together cover almost nothing in the pharmacy, and the enrollment window for that is the same December 7 date.
What Florida actually lost
CMS published the 2027 plan data on October 1. Florida goes from 611 Medicare Advantage plans to 560 — 51 fewer, the largest drop of any state.
| 2026 | 2027 | |
|---|---|---|
| Medicare Advantage plans in Florida | 611 | 560 |
| Plans nationwide | 5,553 | 5,532 |
| US counties with no Advantage plan at all | 67 | 181 |
Hold those first two rows next to each other. The country as a whole lost 21 plans. Florida lost 51. The national figure is almost flat because the withdrawals are concentrated, and Florida is where a large share of them landed.
What that does not mean is that anyone here is left without an option. CMS reports that every person with Medicare in Florida still has access to an Advantage plan in 2027. The plans are fewer, not absent. The risk is not that you cannot find coverage; it is that you are moved into something that fits worse than what you had, and you do not notice until your cardiologist is out of network in March.
The order I would do this in
- Confirm which letter you have. Non-renewal, or an Annual Notice of Change. Everything below depends on this.
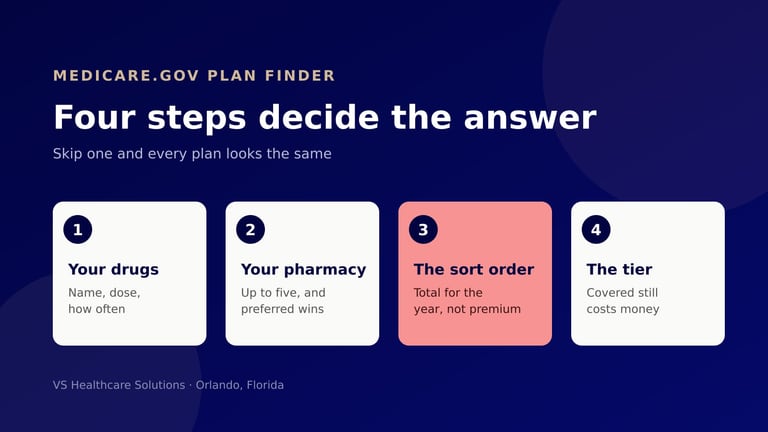
- Write down your doctors and your drugs. Every prescription with its dose and how often you take it, and the pharmacy you actually use. Without this nothing that follows is a real comparison.
- Price both roads, not one. Another Advantage plan, and Original Medicare with Medigap plus a Part D plan. Annual total, not monthly premium — premium, deductible, copays, drug costs, and the out-of-pocket maximum if you have a bad year.
- If Medigap is the answer, apply before you enroll in anything else. The guaranteed issue right is tied to leaving for Original Medicare. Get the policy approved with a January 1 start date.
- Sort out Part D in the same conversation. It is a separate application with the same December 7 deadline.
- Keep every letter and envelope until the new coverage is confirmed in writing.
Rather not do this alone?
This is the exact comparison I do with clients at no cost to them — carriers pay the commission whether you use an agent or enrol yourself, and the premium is identical either way. Book a 20-minute call and bring the letter.
The mistakes I see every November
Taking the first replacement offered. When a plan non-renews, members are often crosswalked or marketed into a specific successor plan. It may be fine. It is not chosen for you on the basis of your doctors or your prescriptions, and accepting it quietly spends your Medigap right.
Assuming a worse plan counts. It does not. Benefit cuts in an Annual Notice of Change give you no guaranteed issue right, however unfair that feels.
Waiting for February because the window exists. It exists, and it starts your coverage February 1. January without drug coverage is a month of paying retail.
Letting the 63 days run while you think about it. This is the one that cannot be fixed afterwards. Every other decision here can be revisited in some form — the Medigap right cannot. When it is gone, it is gone until something else in your life triggers a new one.
Frequently asked questions
How do I know if my Medicare Advantage plan is non-renewing for 2027?
The plan must write to you. The letter says the plan is leaving Medicare or your service area and that coverage ends after December 31, 2026. This is different from the Annual Notice of Change, which every plan sends by September 30 and which describes changes to a plan that is continuing.
Does a non-renewal give me the right to buy Medigap without health questions?
Yes, in most cases — but only if you move to Original Medicare. CMS states that you have this guaranteed issue right if your plan is leaving Medicare, stops giving care in your area, you move out of its service area, or its network changes significantly, and adds that you only have the right if you switch to Original Medicare rather than joining another Advantage plan.
How long do I have to buy the Medigap policy?
You can apply as early as 60 days before your Advantage coverage ends, or by the date in your plan’s termination notice, and no later than 63 days after the coverage ends. The Medigap policy cannot start until your Advantage coverage has ended.
Which Medigap plans am I guaranteed?
Medigap Plan A, B, C, D, F or G sold by an insurance company in your state. Plans C and F are closed to anyone who became eligible for Medicare on or after January 1, 2020; if that is you, the right is to Plan D or Plan G instead.
What if I miss December 7?
If your plan is non-renewing you have a further federal right to join another Medicare health plan through the last day of February 2027. Coverage begins the first of the month after you enroll, so enrolling in January means coverage from February 1 and a month without drug coverage.
If I pick another Advantage plan now, can I switch to Medigap later?
You can apply, but not with the guaranteed issue right — that one is spent. Outside a guaranteed issue situation a Florida Medigap insurer can use medical underwriting and can decline you. You could switch to a different Advantage plan between January 1 and March 31, but that window does not restore the Medigap right.
Will I definitely pay more in 2027?
Not necessarily. Premiums, networks and drug tiers all move, and for some households the replacement is cheaper. The only way to know is to price your own drugs and doctors against both roads. The Part D parameters are set: a maximum deductible of $700 and a $2,400 annual out-of-pocket cap for 2027, against $615 and $2,100 in 2026.
Is there free help in Florida?
Yes. SHINE — Serving Health Insurance Needs of Elders — is Florida’s State Health Insurance Assistance Program and gives free, unbiased counselling at 1-800-96-ELDER. They do not sell anything. Neither obligation conflicts with getting a second opinion from an agent.
One letter, one decision, one deadline that does not come back
Most of what happens during open enrollment is reversible. You can change plans next year. You can switch Advantage plans in the spring. You can adjust a drug plan when your prescriptions change.
The guaranteed issue right is the exception. It opened when that letter was printed and it closes 63 days after your coverage ends, and there is no appeal, no hardship exception and no second look. Whether you use it or decide against it, decide on purpose.
You can see how we help with Medicare, or reach me directly.
- Centers for Medicare & Medicaid Services. Medicare & You 2027, page 102, “What are my rights if my plan stops participating in Medicare?” — coverage ends after December 31; choose another plan October 15 to December 7 with coverage beginning January 1; a special right under federal law to join another Medicare health plan until the last day in February; and the right under federal law to buy certain Medigap policies within 63 days after plan coverage ends.
- Centers for Medicare & Medicaid Services. Choosing a Medigap Policy: A Guide to Health Insurance for People with Medicare (publication 02110), pages 17–18 — guaranteed issue right where a Medicare Advantage plan is leaving Medicare, stops giving care in the area, the enrollee moves out of the service area, or the network has a significant change; the right to buy Medigap Plan A, B, C, D, F or G sold in the state; application from 60 days before coverage ends, or by the date in the plan’s termination notice, and no more than 63 days after coverage ends; Medigap cannot start until Advantage coverage ends; and the limitation that the right applies only on switching to Original Medicare rather than joining another Advantage plan.
- Same publication — Plans C and F are no longer available to people new to Medicare on or after January 1, 2020, who have the right to buy Plan D or G instead; and the guidance to keep letters, notices, claim denials and the postmarked envelope as proof of the right.
- Medicare & You 2027, page 3216 reference — the Annual Notice of Change must reach members by September 30.
- Medicare & You 2027 — Medicare Advantage Open Enrollment Period, January 1 to March 31.
- Centers for Medicare & Medicaid Services, Contract Year 2027 Medicare Advantage and Part D landscape data, published 1 October 2026 — Florida from 611 to 560 Medicare Advantage plans; 5,553 to 5,532 plans nationwide; US counties with no Medicare Advantage plan rising from 67 to 181; and CMS’s statement that every person with Medicare in Florida has access to a Medicare Advantage plan in 2027.
- Centers for Medicare & Medicaid Services, Contract Year 2027 Part D benefit parameters — $700 maximum deductible and $2,400 annual out-of-pocket threshold, against $615 and $2,100 for 2026.
- Florida Department of Elder Affairs. SHINE program, 1-800-96-ELDER.